Filing a Roof Insurance Claim in Cedar Hill, TX
You have a storm date, damage you can see, and a claim to file. What decides a roof insurance claim is the record that exists before anyone repairs anything, so start that record now.
What a roof insurance claim runs on
An insurance claim on a roof is decided by what the adjuster can see, and by the time an adjuster gets there, the roof they see has often already been fixed. The order that protects a claim is simple: document what is there, file with the carrier, let the adjuster look at the damage, and only then move to permanent repair.
Skip that order and there is no going back. A shingle that has already been replaced cannot be un-replaced, and a repair made before anyone documented the damage leaves the carrier weighing your word against nothing. That order asks only that somebody look at the roof and write down what is there before anyone repairs it.
A roofer who has already walked the roof can be there when the adjuster does, standing alongside their own photographs and notes. The claim itself stays yours: what the carrier approves is between you and them, and nobody on this side of it decides that.
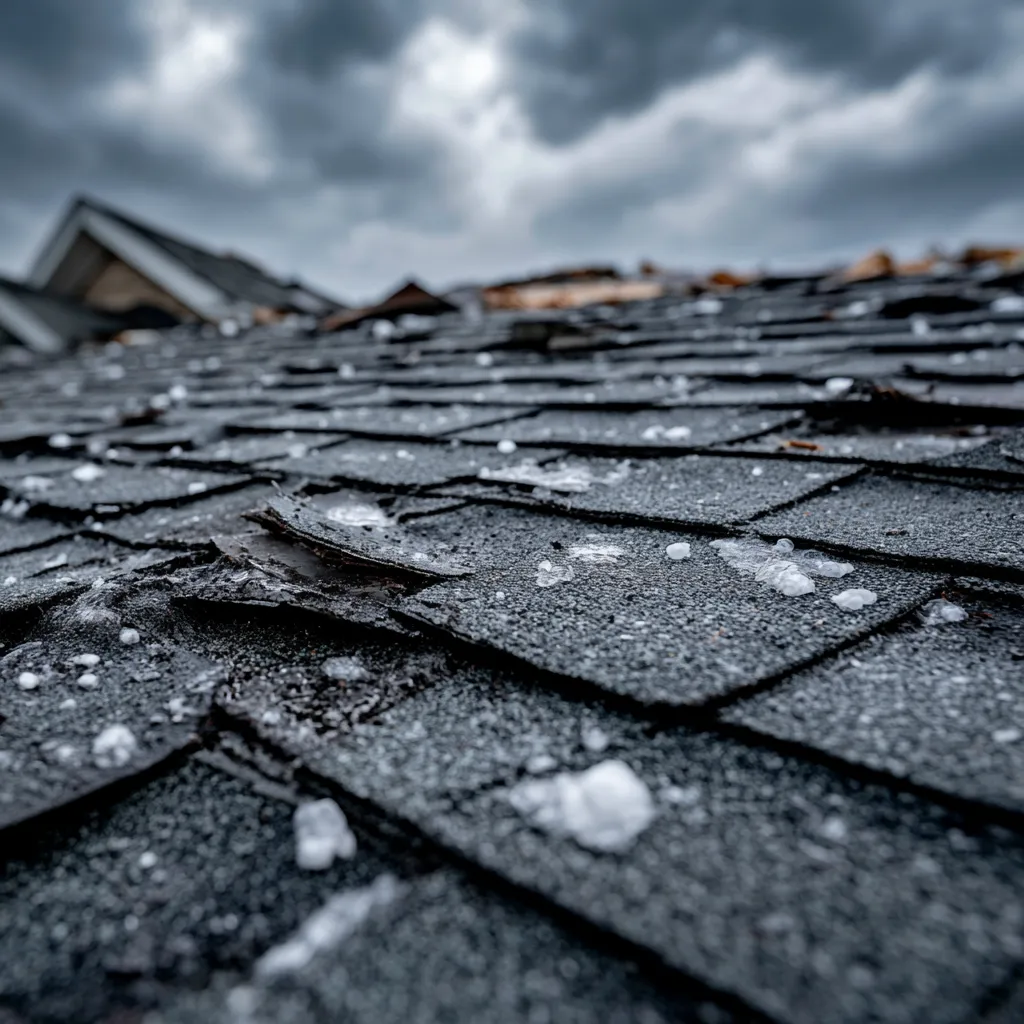
What strengthens a Cedar Hill roof insurance claim
None of this is complicated, and most of it takes a few minutes before anyone else is involved.
- Photograph before anything moves: Take pictures from the ground and from inside the house before any covering, cleanup, or repair happens. Once something is moved or replaced, no photograph can put it back the way the storm left it.
- Write down the storm date: Note the exact date while it is still easy to remember. Many policies measure their filing deadline from that date, so an approximate memory later is a weaker record than a date written down now.
- Keep receipts for temporary protection: Reasonable steps to stop further damage, like a tarp or a cover, are usually a policy duty rather than an extra cost you absorb. Save the receipts, because they typically fold into the same claim as the repair.
- Get a claim number: Filing with the carrier produces a claim number and a list of what has to come in writing. Ask for both up front instead of assuming they will show up later.
- Let the adjuster see it first: Permanent repair work should wait until the adjuster has looked at the roof in the condition the storm left it. Once the work is done, the adjuster is assessing a description instead of the damage itself.
- Check your policy's deadline language: Filing windows exist and they vary by policy, so check the claims section instead of assuming a number you heard somewhere. A missed deadline can close a claim regardless of how bad the damage was.
Actual cash value or replacement cost: know which one you hold
Two different ways an insurer can settle a roof claim, and most homeowners never learn which one is in their policy until the check arrives. Either way it was written into the policy long before the storm, so now is the time to look it up.
Roof insurance claim questions Cedar Hill homeowners ask
Straight answers, in the order a claim moves. None of them decide what your carrier will do.
Q1What's the difference between actual cash value and replacement cost coverage?
Q2How long do I have to file a claim after a storm?
Q3What's the difference between cosmetic and functional roof damage?
Q4Can repairs start before the adjuster sees the roof?
Q5Will filing a claim guarantee it gets approved?
Start your Cedar Hill roof claim record
Send the storm date and what you can see today, before anything gets covered or replaced. That record is what a claim gets judged on later, and your claim stays yours throughout.